Israel Considers Shifting from Group Long-Term Care Insurance to Personal Savings Accounts
Translated & summarized from Bizportal by baba
The story in 5 lines · by baba
- Israel may replace group long-term care insurance with personal savings accounts.
- The current system is strained by a significant increase in claims.
- A proposed hybrid model combines personal savings with insurance coverage.
- Key details like mandatory contributions and transition plans are undecided.
- Both health fund and public long-term care systems face funding challenges.
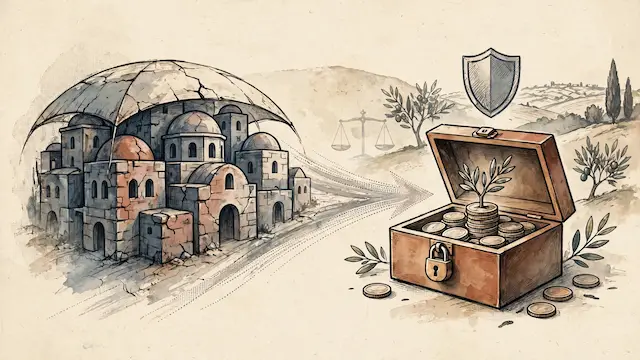
Israel is exploring a significant shift in how it funds long-term care, moving away from the current group insurance model offered by health funds towards a system of personal savings accounts. The existing system, where premiums from all insured individuals fund claims, is facing financial strain due to rising claims, depleted reserves, increased premiums, and stricter eligibility criteria. The proposed model, under review by the Capital Markets Authority, would involve individuals accumulating dedicated savings over their working lives, supplemented by an insurance component to cover cases where insufficient funds have been saved. This change could allow for investment growth over decades and potentially allow beneficiaries to pass on unused balances to heirs.
The current group insurance model, while providing risk diversification, has proven unsustainable. The number of approved long-term care claims in Israel has surged by over 150% between 2012 and 2023, straining the insurance funds. This has led to reduced benefits, stricter qualification requirements, and increased premiums. The private insurance market has also largely withdrawn from offering new long-term care policies since 2019, making health fund insurance the primary option for the public.
Simultaneously, the public long-term care benefit provided by the National Insurance Institute has also seen a threefold increase in annual expenditure between 2018 and 2025, with the number of eligible recipients more than doubling. This indicates a broader systemic challenge in funding long-term care for an aging population.
The proposed personal savings model aims to address these issues by creating individual accounts that grow over time. However, questions remain about whether these savings will be sufficient to cover the high monthly costs of long-term care, which can range from tens of thousands of shekels. The model is being considered as a hybrid system, combining personal savings with an insurance component to cover early-onset disability or prolonged care needs. Key details, such as whether contributions will be mandatory, the contribution rate, employer participation, and tax benefits, are still under discussion. The transition from the old system to the new one, and how existing policyholders' rights will be handled, also remains an open question.
The same event, reported separately by each outlet. Open a few to compare what different newsrooms emphasize — and what they leave out.